📌 FAST-DS 2026 – Points Covered
- OVERVIEW
- Crucial Statutory Benchmarks
- The 4-Step Filing Process with Portal Navigation Paths
- Form Timeline
- Payment Rules & Interest Calculations
- Summary
- Additional Practical Examples: FAST-DS 2026 Payment Timelines & Interest Rules
OVERVIEW
The Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026 (FAST-DS) is a time-bound, online voluntary disclosure scheme available through the official Income Tax e-Filing Portal.
Since failure to make the required payment within the prescribed timeline can render the declaration void and deemed never to have been made, it is important for taxpayers to understand the form sequence, e-filing process, payment timelines and applicable rules.
Crucial Dates to Remember:
|
Milestone |
Statutory Timeline |
Key Rule / Requirement |
|
Valuation Benchmark Date |
March 31, 2026 |
All foreign assets must be valued at Fair Market Value (FMV) as of this exact date per prescribed valuation rules. |
|
Declaration Filing Window |
August 16, 2026 – December 31, 2026 |
Form 1 must be submitted electronically on or before December 31, 2026. |
He 4-Step Filing Process:
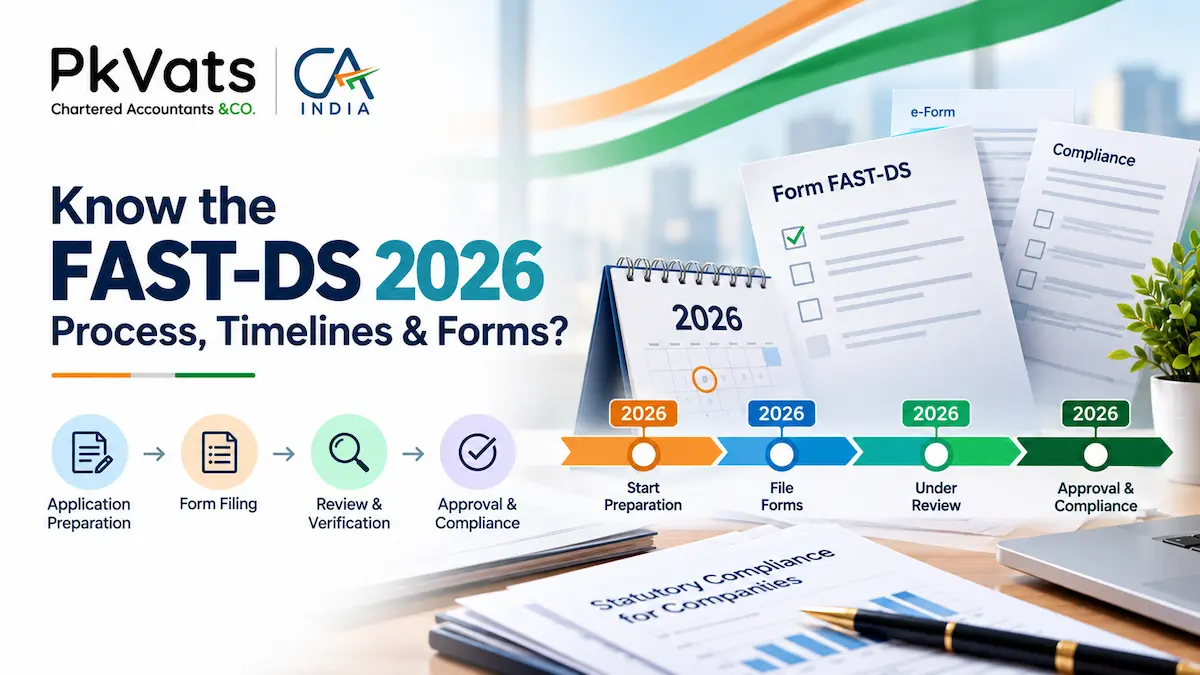
The process involves Form 1 → Form 2 → ITNS 289 (Payment) → Form 3 → Form 4.
The declaration is filed electronically through:
Income Tax e-Filing Portal → Login → e-File → Income Tax Forms → File Income Tax Forms → Forms as per Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (Form 1 of FAST DS 2026)
Forms involved:
→ Form 1 (Declaration by Taxpayer):
The taxpayer submits a detailed online declaration containing asset particulars, acquisition dates, historical residential status, source of funds, and required attachments (valuation reports, foreign brokerage/bank statements).
📍 E-Filing Portal Path
Income Tax e-Filing Portal → Login → e-File → Income Tax Forms → File Income Tax Forms → Under Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (Form 1 of FADS 2026)
→ Form 2 (Determination of Amount Payable):
The Income Tax Authority reviews Form 1 and issues Form 2, specifying the exact tax, penalty, or fixed fee payable under Category 1 or Category 2.
→ Challan ITNS 289 & Form 3 (Intimation of Payment):
The taxpayer pays the determined amount electronically using Challan ITNS 289 and files Form 3 on the e-filing portal to submit proof of payment to the department.
📍 Payment Path:
Income Tax e-Filing Portal → Login → e-File → e-Pay Tax → Select Income Tax Act, 1961 → New Payment → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 (ITNS 289)
→ Form 4 (Certificate of Immunity):
Upon successful verification of payment, the Income Tax Department issues Form 4, granting formal statutory immunity from tax, penalty, and criminal prosecution under the Black Money Act, 2015.
Form Timelines
|
Form |
Timeline |
|
Form 1 |
16 August 2026 to 31 December 2026 |
|
Form 2 |
Within 1 month from the end of the month in which Form 1 is submitted |
|
Initial Payment Period |
Within 2 months from the end of the month in which Form 2 is received |
|
Extended Payment Period |
Additional period of up to 2 months (with 1% interest per month or part thereof) |
|
Form 3 |
Within 4 months from the end of the month in which Form 2 is issued |
|
Form 4 |
Within 1 month from the end of the month in which Form 3 is submitted |
Detailed Payment Timelines & Interest Rules
Initial Payment Period – 2 Months:
The amount determined in Form 2 must be paid within 2 months from the end of the month in which Form 2 is received. No interest is charged during this window.
💡 Example:
→ Form 2 Received Date: September 15, 2026
→ End of Month Benchmark: September 30, 2026
→ Primary Payment Deadline: November 30, 2026
→ Form 2 Demand: ₹30,00,000 (Category 1 60% Tax/Penalty on a ₹50L undisclosed asset)
→ Payment Made On: November 20, 2026
→ Total Amount Payable: ₹30,00,000 (Zero Interest)
Extended Window (Additional period 2 Months):
If payment is delayed beyond the primary window, the taxpayer is granted an additional period of up to 2 months. However, simple interest at 1% per month or part thereof is charged on the unpaid amount for the delay period.
💡 Example:
→ Primary Payment Deadline: November 30, 2026
→ Form 2 Demand: ₹30,00,000 (Category 1 60% Tax/Penalty on a ₹50L undisclosed asset)
→ Payment Made On: January 15, 2027 (Spans 2 partial/full calendar months: Dec & Jan)
→ Total Amount Payable: ₹30,60,000 (₹30,00,000 + ₹30,00,000 × 2% Interest)
Default Condition (Beyond 4 Months):
If full payment (including applicable interest) is not made within 4 months from the end of the month Form 2 was received, the declaration becomes void and is legally treated as if it was never made. Standard penal proceedings under the Black Money Act will apply.
💡 Example:
→ Form 2 Received Date: September 15, 2026
→ Final Statutory Deadline (4 Months from Sept 30): January 31, 2027
→ Status as of February 1, 2027: Payment remains pending or incomplete.
→ Legal Outcome: The Form 1 declaration is declared 100% VOID. The taxpayer loses all statutory immunity under FAST-DS, and the Income Tax Department can initiate standard Black Money Act proceedings (120% tax/penalty levy + criminal prosecution).
In simple words:
Form 2 received → 2 months payment period → delay → Additional period of 2 months (1% per month/part there of interest) → payment is still Unpaid after 4 Months → declaration becomes void.
{Pro Tip: Do not wait until December. Tracing old foreign bank statements and getting certified valuation reports for overseas properties takes time! Initiate your documentation prep early to avoid missing statutory deadlines}
Summary:
Filing under FAST-DS 2026 is an entirely online, 4-step process starting with the taxpayer’s declaration in Form 1 and concluding with a formal Immunity Certificate in Form 4. All foreign assets must be valued as of March 31, 2026, and the declaration portal closes on December 31, 2026. Because failing to pay the Form 2 demand within the maximum 4-month window makes the declaration void, taxpayers should prepare supporting documents immediately to complete payment smoothly.
Additional Practical Examples: FAST-DS 2026 Payment Timelines & Interest Rules
Scenario 1: The “Part of a Month” Interest Rule (Paying Just Days Late)
Rule: Interest under FAST-DS is charged at 1% per month or part thereof. Even a 1-day or 3-day delay into a new calendar month triggers a full 1% interest penalty on the unpaid balance.
- Form 2 Demand Received: October 10, 2026
- Form 2 Demand Amount: ₹1,00,000 (Category 2 Flat Fee)
- Interest-Free 2-Month Deadline: December 31, 2026 (2 months from end of October)
- Actual Payment Date: January 3, 2027 (Delayed by only 3 days into January)
- Interest Calculation: Since January represents a “part of a month,” a full 1% simple interest applies (1% × ₹1,00,000 = ₹1,000).
- Total Amount Paid via ITNS 289: ₹1,01,000
Scenario 2: Staggered / Partial Payments Across Both Windows
Rule: If a taxpayer pays a portion of the demand within the primary 2-month window and settles the remaining balance in the extended window, interest applies only to the unpaid balance for the extended period.
- Form 2 Demand Received: September 20, 2026
- Form 2 Demand Amount: ₹60,00,000 (Category 1 Tax/Penalty on a ₹1 Crore asset)
- Primary Deadline (0% Interest): November 30, 2026
- Payment Step 1 (Nov 15, 2026): Taxpayer pays ₹40,00,000 within the primary window. (Remaining Balance = ₹20,00,000)
- Payment Step 2 (Jan 20, 2027): Taxpayer pays the remaining ₹20,00,000 in the extended window (delayed across 2 calendar months: December & January).
- Interest Calculation: Interest = 2% × ₹20,00,000 (Unpaid Balance)} = ₹40,000
- Total Amount Paid: ₹60,40,000 (₹40,00,000 + ₹20,40,000)
Scenario 3: Late-Window Filing (Filing Form 1 in Dec 2026, Paying in 2027)
Rule: Even though the Form 1 declaration window closes on December 31, 2026, the issuance of Form 2 and the subsequent 4-month payment cycle continue legally into 2027.
- Form 1 Submitted On: December 28, 2026
- Form 2 Issued & Received: January 20, 2027
- End of Month Benchmark: January 31, 2027
- Primary Payment Window (0% Interest): February 1, 2027 to March 31, 2027
- Extended Payment Window (1% Monthly Interest): April 1, 2027 to May 31, 2027
- Outcome: If paid on or before March 31, 2027, the taxpayer pays zero interest, even though the payment occurs in calendar year 2027.
Scenario 4: The Financial Disaster of a Void Declaration (Category 1 Default)
Rule: Failing to pay the full demand plus applicable interest within 4 months from the end of the month Form 2 was received makes the declaration 100% void. The paid portion is not recognized as a valid FAST-DS settlement, and full Black Money Act (BMA) penalties are triggered.
- Asset Profile: Unreported foreign bank balance of ₹80,00,000 (Category 1)
- Form 2 Demand Issued: ₹48,00,000 (60% tax + penalty) received on August 12, 2026
- Final Statutory Extended Cut-off: December 31, 2026 (4 months from August 31)
- Taxpayer Action: The taxpayer pays ₹30,00,000 in November 2026 but fails to arrange the remaining ₹18,00,000 (plus interest) by December 31, 2026.
- Legal Consequence:
- The Form 1 declaration is declared VOID.
- Statutory immunity under FAST-DS is forfeited.
- The Income Tax Department initiates standard Black Money Act proceedings:
→ Full BMA Tax & Penalty Levy: 120% × ₹80,00,000 = ₹96,00,000
→ Prosecution: Criminal proceedings under Section 49/50 of BMA (3 to 10 years imprisonment).